By

August 11, 2026
Do I Pay VAT on Goods Imported Into the UK?
Yes, VAT is normally payable on goods imported into the UK, although exactly how VAT is charged depends on the value of the goods, where they come from, who is importing them and whether the importer is VAT registered.
For goods imported into Great Britain — England, Scotland and Wales — from outside the UK, Import VAT will normally apply. Different rules can apply to Northern Ireland because of its separate arrangements for movements involving the EU.
For businesses, an important distinction is that Import VAT may often be recoverable by a VAT-registered business, while Customs Duty generally remains an import cost.
Import VAT is VAT charged when goods are imported into the UK.
For example:
UK company
↓
Buys stock from China
↓
Goods enter Great Britain
↓
Import VAT may become due
Import VAT is normally charged at the same VAT rate that would apply if the goods were supplied within the UK.
This means the rate depends on the type of goods being imported.
No.
Import VAT and Customs Duty are separate charges.
Customs Duty depends on factors including:
Import VAT is calculated separately using the relevant VAT value.
A shipment can therefore have:
Customs Duty
Import VAT
Customs clearance charges
The fact that Customs Duty is 0% does not automatically mean there is no Import VAT.
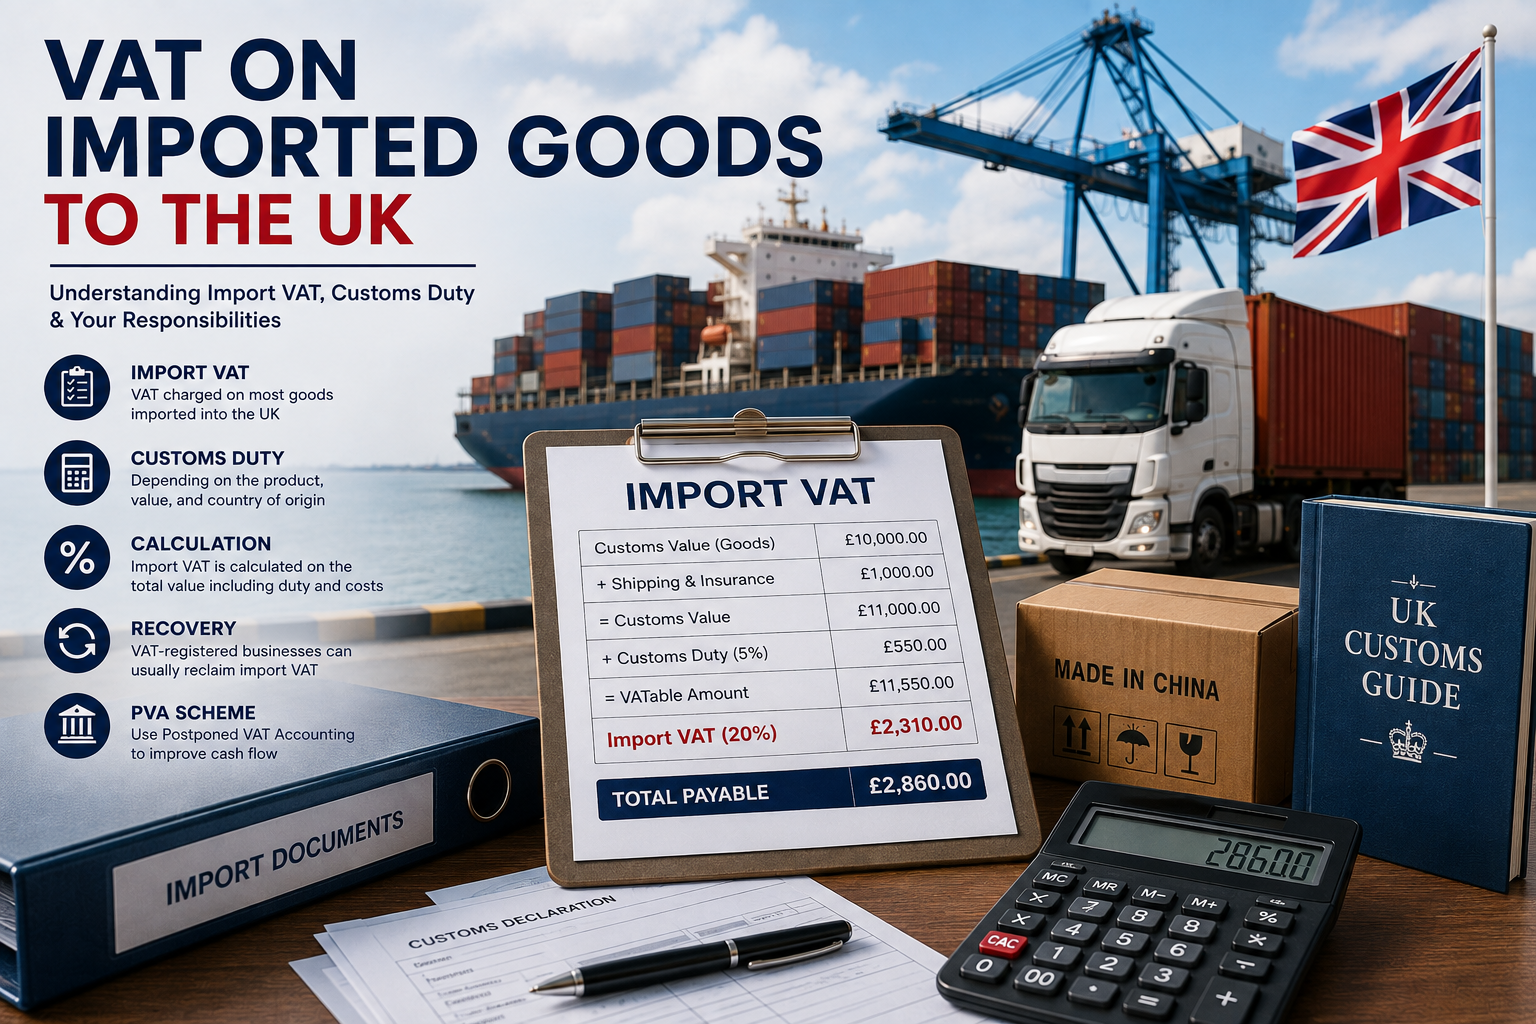
Import VAT is not necessarily calculated only on the supplier's invoice price.
The VAT value can include:
Customs value of goods
Customs Duty
Certain transport and other costs
=
Import VAT value
The applicable VAT rate is then applied.
Suppose a UK company imports goods with:
Customs value: £10,000
Customs Duty: £500
Assume the VAT value after including the relevant costs is:
£10,500
If VAT applies at 20%:
£10,500 × 20% = £2,100
Potential Import VAT:
£2,100
This is a simplified example. The actual VAT value can include postage, packaging, insurance, duty and other relevant costs.
Potentially, yes.
This is a common misunderstanding.
For example:
Customs value: £10,000
Customs Duty: 0%
Customs Duty payable: £0
Import VAT can still apply.
If the relevant VAT value is £10,000 and VAT applies at 20%:
Import VAT = £2,000
Therefore:
0% Customs Duty ≠ 0% Import VAT
Potentially, yes.
If your business is VAT registered and the imported goods are used for qualifying business purposes, eligible Import VAT can generally be recovered subject to the normal VAT rules.
This creates an important distinction:
Import VAT → potentially recoverable
Customs Duty → generally remains a business cost
The company must have appropriate evidence to support its Import VAT recovery.
VAT-registered businesses may be able to use Postponed VAT Accounting (PVA).
PVA allows the business to account for Import VAT through its VAT Return instead of paying the VAT upfront at the border and recovering it later.
The process can look like:
Import goods
↓
Import VAT calculated
↓
Declare Import VAT on VAT Return
↓
Recover eligible VAT on the same VAT Return
This can provide an important cash-flow advantage for businesses that import stock regularly.
No.
Postponed VAT Accounting does not remove the VAT liability.
It changes when and how the Import VAT is accounted for.
Where the business is entitled to recover all the Import VAT, the VAT declared and reclaimed on the same VAT Return may effectively offset each other.
Normal VAT recovery rules still apply.
If your business is not VAT registered, Import VAT can still be payable.
However, you generally cannot reclaim it through a VAT Return.
For example:
Products: £10,000
Import VAT: £2,000
If the business cannot recover the VAT, the £2,000 effectively becomes part of the cost of importing the products.
This is particularly important when calculating profit margins.
Normally, Import VAT can apply when goods are imported from China into Great Britain.
Depending on the products, you could potentially have:
Customs Duty
Import VAT
Customs clearance fees
The Customs Duty rate depends on the commodity code and applicable tariff measures.
Import VAT is calculated separately.
Import VAT can also apply when goods are imported from the United States into Great Britain.
The same general principle applies:
Goods enter Great Britain
↓
Customs declaration
↓
Customs Duty calculated where applicable
↓
Import VAT calculated
The supplier's country does not remove the UK Import VAT requirement.
Goods entering Great Britain from EU countries are generally treated as imports for VAT purposes.
Import VAT can therefore apply.
However, Customs Duty may be reduced or eliminated where goods qualify for preferential treatment under the applicable UK-EU rules of origin.
Import VAT and Customs Duty should still be considered separately.
Special VAT rules apply to certain consignments worth £135 or less.
For goods outside the UK when sold directly to customers in Great Britain, VAT may generally be collected at the point of sale rather than as Import VAT at the border.
For consignments worth more than £135, the normal import VAT and customs rules generally apply.
Different rules can also apply where goods are sold through an online marketplace.
Potentially.
Special rules apply to certain overseas goods sold to UK customers through online marketplaces.
For qualifying consignments worth £135 or less, the online marketplace may be responsible for charging and accounting for UK VAT at the point of sale.
This is particularly relevant to ecommerce businesses selling through international marketplaces.
It depends on where the goods physically enter.
For example:
UK company
↓
Chinese supplier
↓
US customer
The goods never enter the UK.
There is therefore no UK import simply because the seller operates a UK company.
But:
Chinese supplier
↓
UK customer
can create UK VAT and customs consequences.
The exact treatment depends on the value of the consignment and how the sale is structured.
Businesses importing goods should retain appropriate records, including:
If PVA is used, the monthly postponed Import VAT statement provides information needed to account for the VAT through the VAT Return.
If PVA is not used, VAT-registered businesses may need a C79 Import VAT certificate to support recovery of Import VAT.
Businesses should avoid:
Generally, yes. Import VAT normally applies to goods imported into Great Britain from outside the UK, subject to specific VAT rules and reliefs.
Import VAT can apply when goods from China enter the UK.
Yes, Import VAT can apply to goods imported from the USA into Great Britain.
Goods entering Great Britain from EU countries can generally be subject to Import VAT.
A VAT-registered business may generally recover eligible Import VAT subject to the normal VAT recovery rules.
Customs Duty is generally not reclaimed as VAT and normally forms part of the cost of importing the goods.
PVA allows eligible UK VAT-registered businesses to declare and potentially recover Import VAT through the same VAT Return rather than paying it upfront.
VAT can still apply. For certain consignments of £135 or less, VAT is collected at the point of sale rather than through the normal Import VAT process.
So, do you pay VAT on goods imported into the UK?
In most cases, VAT needs to be accounted for when goods are imported, although the way it is collected depends on the transaction.
For a typical commercial import:
Buy goods overseas
↓
Goods enter Great Britain
↓
Customs Duty calculated where applicable
↓
Import VAT calculated
↓
VAT paid or accounted for using PVA
↓
Eligible VAT-registered business may reclaim Import VAT
The key distinction for businesses is:
Import VAT may be recoverable
while:
Customs Duty generally remains an import cost.
If your company imports goods regularly and is UK VAT registered, Postponed VAT Accounting can be particularly useful because it allows qualifying Import VAT to be declared and recovered through the VAT Return.
This article provides general information only and does not constitute tax, customs, accounting or legal advice. VAT rules can change and special rules apply to certain goods and Northern Ireland. Check current HMRC guidance for your specific import.